Why M&A Winners Are Losing to AI‑Native Competitors
For years, the playbook for market consolidation was to acquire competitors, preserve their brand identity, grow your share, and defend that position through scale. The strategy worked because size itself was a competitive moat, but AI is now exposing how quickly that advantage can erode when the technology underneath remains fragmented.
Across industries where one platform has absorbed several competitors, organizations that consolidated their markets without consolidating their technology are finding that the scale can now work against them. The problem lies in what was left undone after those acquisitions.
A Unified Surface Can Hide a Fragmented Foundation
When a platform acquires a competitor, the instinct is to preserve the brand and leave the product experience intact. That can be commercially sound.
Underneath, however, something harder to fix can build up quietly. Each acquired product may retain its own database, and data model, while customer records live in parallel systems with no shared source of truth, and engineering teams inherit overlapping, inconsistent codebases where a change in one brand creates side effects in another.
Integration debt has long been a known cost of acquisition, with AI now amplifying its consequences.
Fragmented Data Limits AI Performance
AI models struggle to produce consistent output when they draw from disconnected databases. A fragmented foundation means slower feature development, since every capability must be rebuilt for each product's data layer, and insights from one brand cannot easily improve the experience across the wider portfolio.
This creates a trap in which the acquirer's own integration liability slows it down against the very competitors its scale should otherwise help it outperform.
Consider a multi-brand funeral services company built through acquisition. An AI-native entrant can out-build it on every front-end feature, with faster obituary publishing, cleaner booking flows, and more responsive family support) because a single product is easier to make coherent.
The incumbent cannot match that speed while its brands still run on separate systems. For now, greater coherence can matter more than greater scale.
The Liability Can Become the Moat
The same liability slowing down the incumbent today also contains an advantage an AI-native entrant cannot easily replicate.
That funeral services company is sitting on decades of accumulated obituary, family, and service records across every market it operates in. A newer competitor may be able to out-build features, but it cannot recreate forty years of accumulated data.
Once that data is unified, it stops being dead weight and becomes an asset that fragmented or newly built rivals cannot buy or build their way into.
Building the Abstraction Layer
In practice, this means building an abstraction layer that normalizes every acquired product's data into a common schema, creates a single repository AI can draw from, and lets each brand keep its own front end while new AI capabilities can be deployed across the portfolio.
Legacy systems can remain in place, avoiding the disruption of a full replacement. The result is one shared nervous system beneath distinct brand experiences, with each brand retaining its identity. Underneath, they share the same intelligence, and eventually, the same accumulated dataset.
We often approach this first as a data and architecture problem, aligning integration standards, pipeline architecture, governance, and the business use cases the foundation needs to support.
AI Agents as the Integration Accelerator
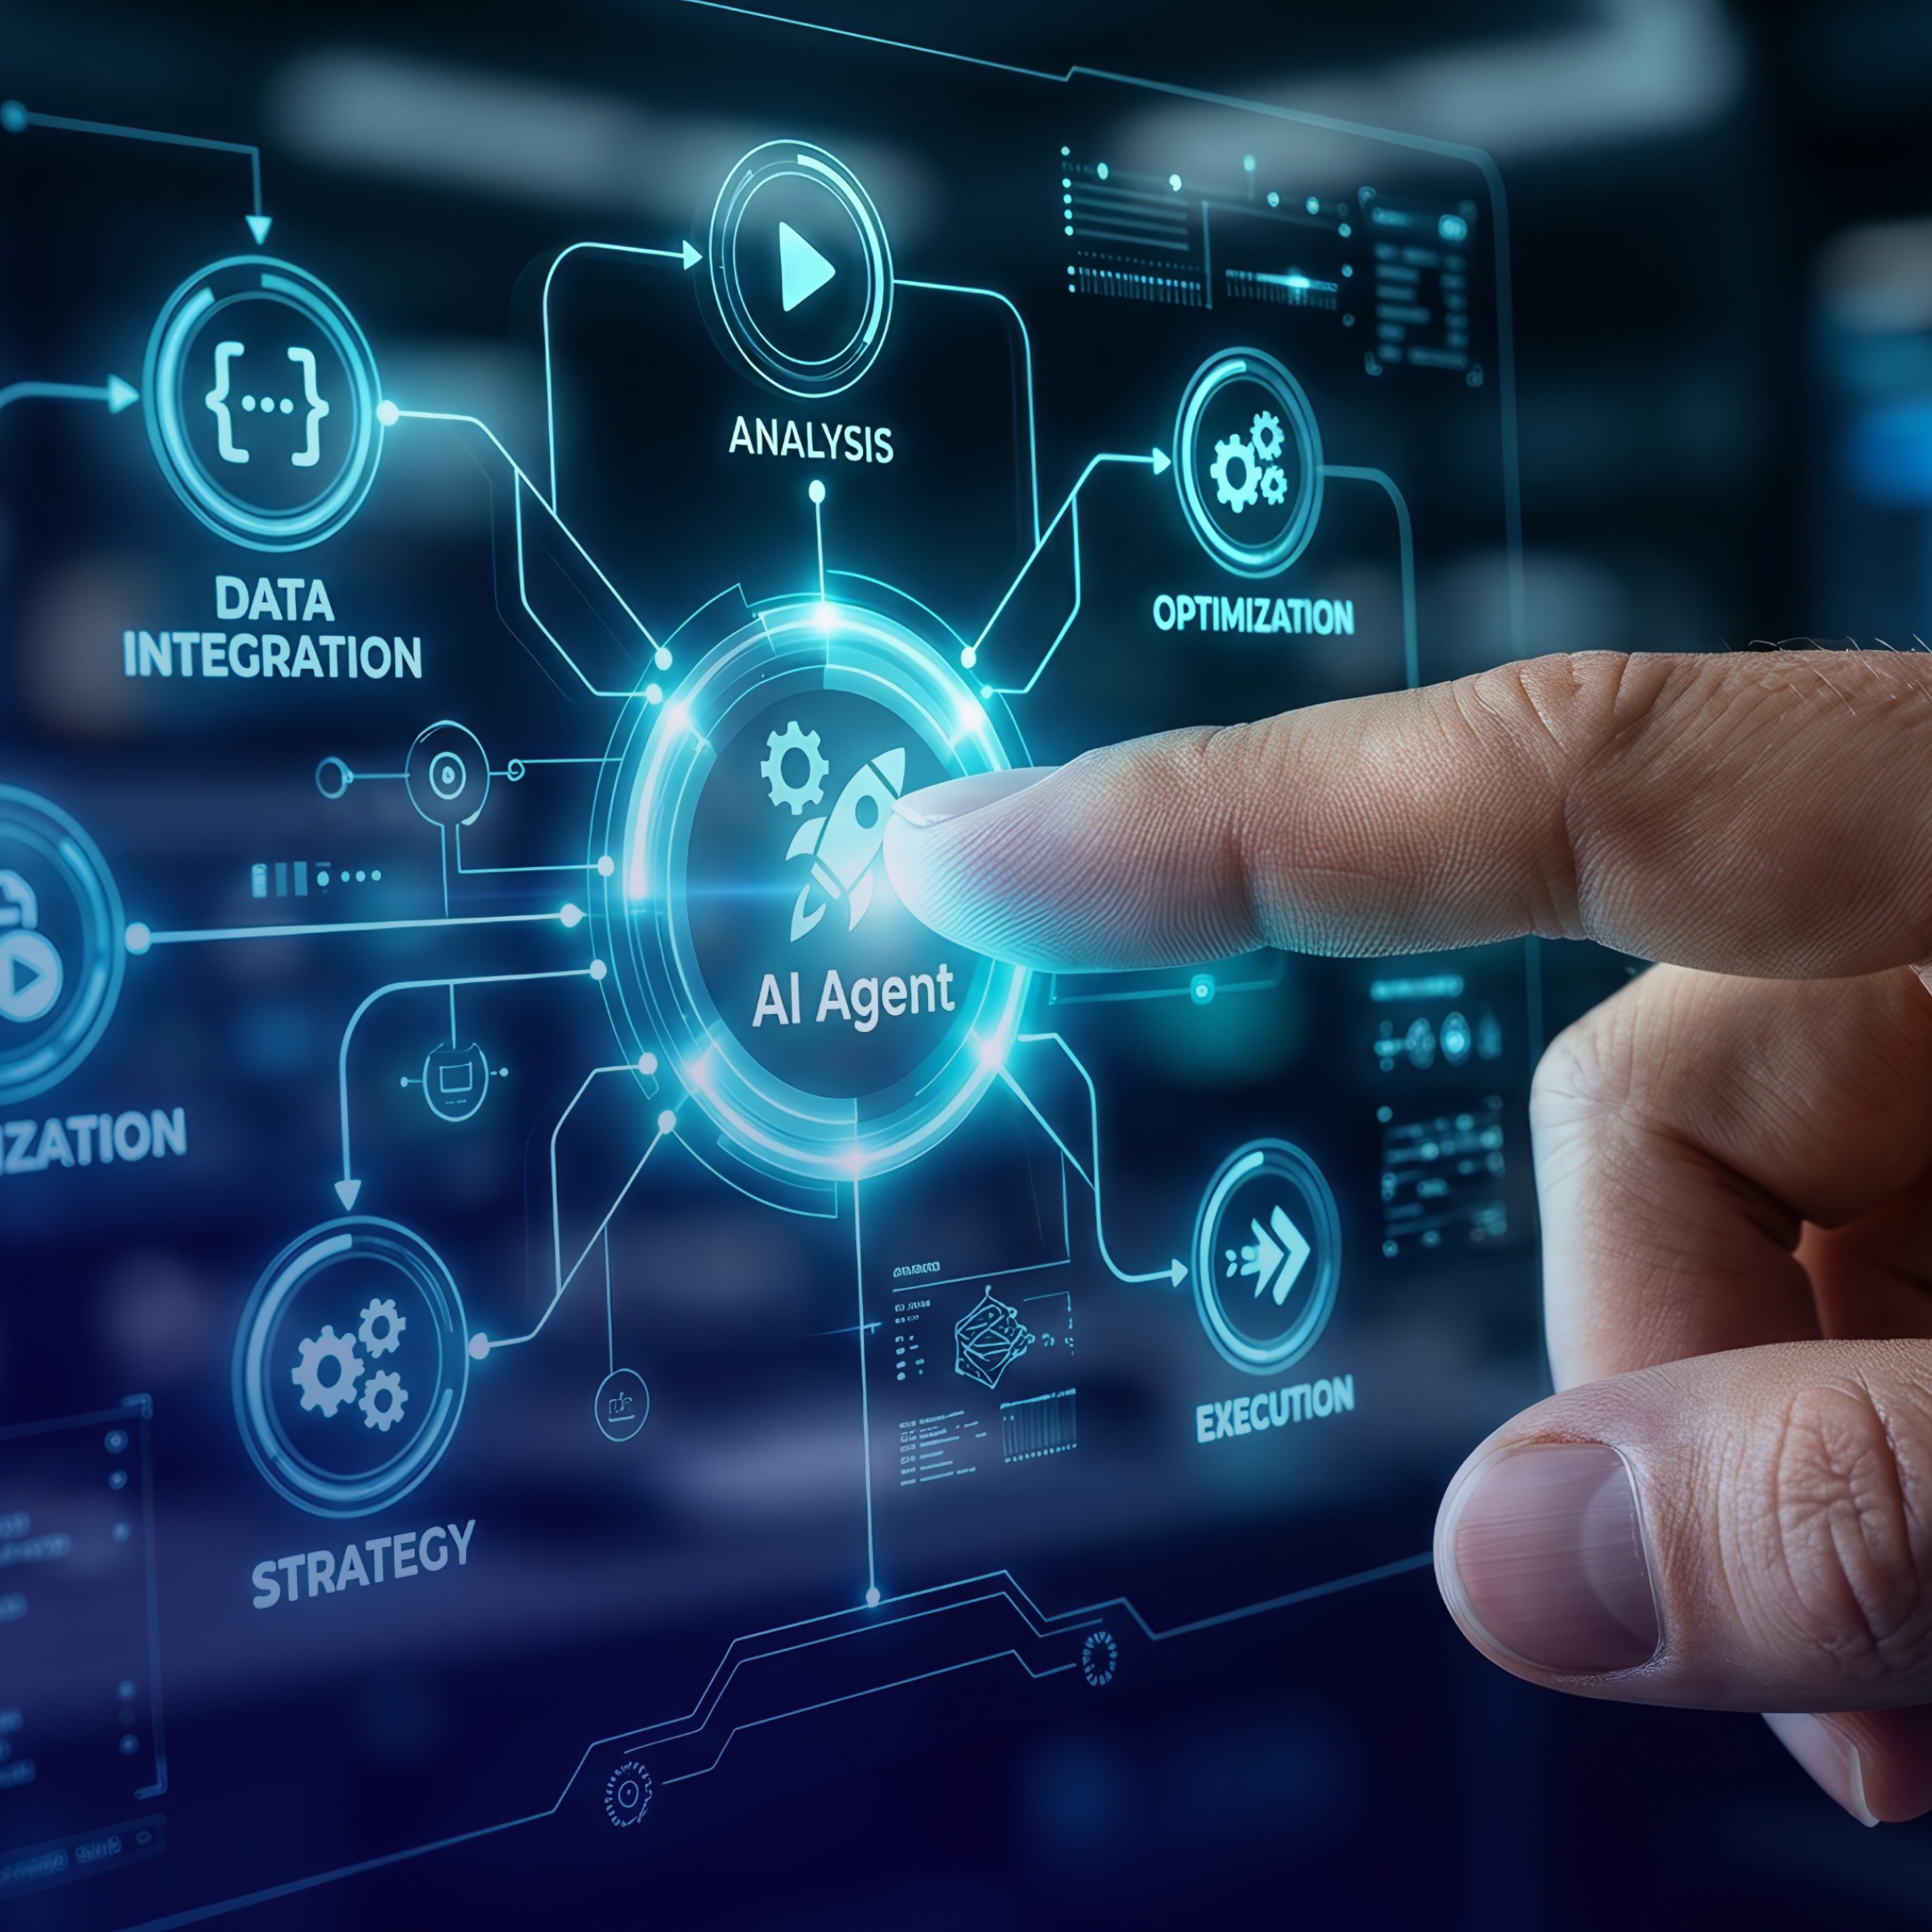
Once that foundation exists, AI agents can accelerate the integration itself. Data reconciliation agents resolve inconsistencies between legacy databases continuously. Customer experience agents deliver coherent interactions no matter which brand a user touches. Product intelligence agents surface insights across the whole portfolio, drawing on data from multiple brands. Quality agents catch when a change in one brand's system quietly breaks another.
Consider a scenario in which a five-brand retail group cuts its post-acquisition AI timeline from a year to under a quarter using a data reconciliation agent that resolves conflicting customer records across five legacy databases overnight.
The abstraction layer makes the speed possible, with the agent operating on top of a foundation already designed for shared data and interoperability.
The Cost of Waiting
Every quarter an organization delays integration, engineering debt compounds, user experiences drift further apart between brands, and the AI readiness gap with competitors widens.
An organization with dominant market share can still lose the advantage of scale when it is running on seven disconnected databases, while a leaner rival moves at full speed.
Without unified data, scale becomes weight; once that data is unified, the same scale can become a moat.
The greater value comes from applying AI to the right problem and using it where it can remove structural constraints. An organization that keeps adding AI features on top of a fragmented foundation is compounding the same structural liability, regardless of how many features it ships.
The wiser move is to point AI at the integration itself first, right after the deal closes, using it to strengthen the foundation before attention shifts to matching whatever the market’s newest entrant builds next.
3 Things Organizations Must Do
- Make integration a Day One priority. Every deal needs an explicit plan for the abstraction layer before it is considered complete.
- Appoint one owner for unified data architecture with cross-brand authority and a clear mandate.
- Use AI to accelerate the integration itself from the outset. Organizations that do this close the gap in months; those waiting for a full re-platform will still be waiting when the landscape shifts again.
The acquisition strategy created a market position. The integration strategy decides whether that position holds, and whether it becomes an advantage competitors cannot easily replicate. The brands best positioned after consolidation are those that become coherent fastest and turn that coherence into an asset.
News & Insights
Featured Perspectives